

Health insurance engineered for your bottom line
Most small and mid-sized businesses are priced on market averages, not their actual workforce. Level-funded health plans give qualified employers greater transparency, predictability, and control over their healthcare spend.

Smarter health plans without paying for everyone else
Level-funded plans offer predictable monthly payments without one-size-fits-all pooled pricing. Nationwide, 42% of small businesses (3–199 employees) have already made the switch. Many brokers don’t show a fair comparison to smaller groups due to the extra administrative work for them.


Who you'll work with
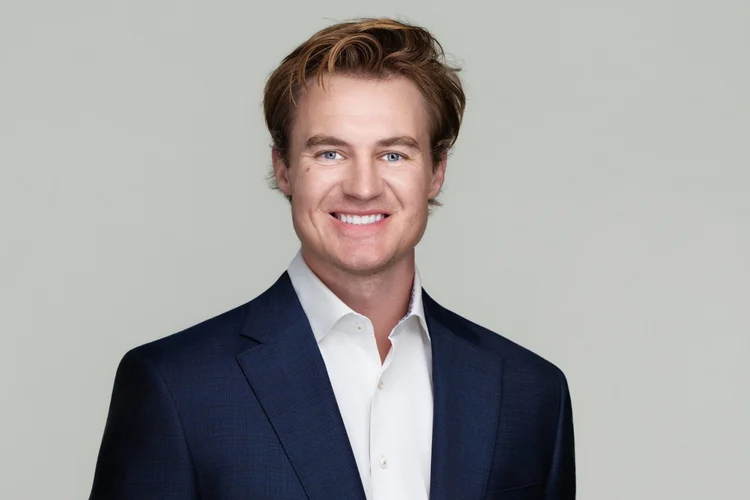
Founded by a 7-year insurance carrier insider
Nick Hamilton worked alongside UnitedHealthcare's underwriting and rate-setting teams before founding Crestin. He knows which parts of a renewal are fixed and which can be negotiated, and he handles every client himself.
Meet Nick
The default is costly
Most employers simply renew what they already have. In California, fully insured small group coverage remains the default, largely because it’s easier to quote, easier to renew, and rarely requires deeper claims-based analysis.
Meanwhile, costs continue to climb. For 2026, filings show double-digit premium pressure in the small-group market, with a median proposed increase of around 14% nationally.
If you’re a small business, you deserve to see all the available options.

Our difference
We help employers regain control of their second largest expense. Working with small and mid-market companies, we transition organizations from pooled, market average pricing to underwritten health plans designed around their specific workforce.
